9 November 2026
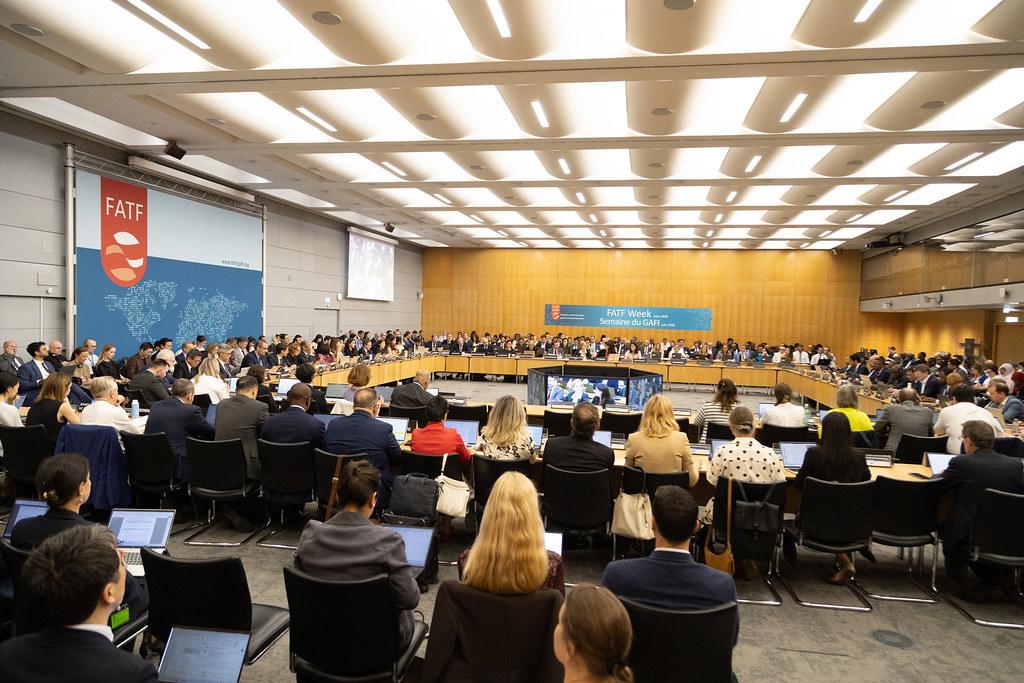
FATF Plenary meeting in Paris. Source: Financial Action Task Force (FATF).
The Financial Action Task Force (FATF) is increasing pressure on jurisdictions that have failed to implement effective anti-money laundering and counter-terrorist financing controls for virtual assets. At its October 2026 Plenary in Paris, FATF agreed to launch a new targeted review and accelerated follow-up process focused on jurisdictions with materially important virtual-asset sectors where implementation of FATF standards remains inadequate.
The initiative matters far beyond governments and regulators. For crypto exchanges, custodians, payment providers, stablecoin businesses and other Web3 companies operating across borders, the regulatory quality of the jurisdictions in which counterparties, customers and service providers operate is increasingly becoming a commercial and legal risk in its own right.
From global standards to implementation pressure
FATF brought virtual assets and Virtual Asset Service Providers (VASPs) within its international AML/CFT framework through amendments to Recommendation 15 beginning in 2018 and 2019. Since then, many jurisdictions have adopted legislation regulating crypto businesses.
Implementation, however, remains uneven. FATF’s Seventh Targeted Update on Virtual Assets and VASPs, published in July 2026, found that while implementation continues to improve, significant gaps remain. FATF reported that 83% of surveyed jurisdictions had enacted legislation implementing the Travel Rule, compared with 73% the previous year.
The Travel Rule requires regulated virtual-asset businesses to obtain and transmit specified information concerning the originator and beneficiary of qualifying transactions. But adopting legislation is only part of the problem.
The October Plenary made clear that FATF is now increasingly concerned about whether jurisdictions are actually supervising and enforcing those requirements. The new targeted review will therefore concentrate particularly on jurisdictions with materially important VASP activity and will examine their implementation status more closely. Initial results are expected in June 2027, followed by further results in October 2027.
Why jurisdiction risk matters to crypto businesses
Crypto transactions are inherently cross-border. An exchange incorporated in one country may serve customers in several others, interact with custodians elsewhere and transfer assets to wallets connected to service providers across multiple jurisdictions.
That architecture means weaknesses in one jurisdiction can create risks for businesses operating elsewhere. A regulated exchange may, for example, face heightened exposure where a counterparty VASP operates in a jurisdiction that does not effectively implement the Travel Rule, customer due diligence or sanctions controls.
The issue is therefore no longer simply whether the exchange itself has an AML policy. Companies increasingly need to ask whether their counterparties and jurisdictions present an acceptable AML risk. For international crypto businesses, this may require more sophisticated geographic risk assessment, enhanced due diligence, transaction monitoring and contractual controls over third-party service providers. It can also affect commercial decisions about which markets to enter and which counterparties to accept.
FATF’s concern extends beyond conventional money laundering
The October Plenary specifically identified the use of virtual assets in fraud, scams, sanctions evasion, money laundering, terrorist financing and proliferation financing. This wider perspective is important.
Crypto compliance is no longer limited to suspicious transaction monitoring or conventional KYC. Sanctions exposure, cybersecurity incidents, fraud networks and illicit payment infrastructure are increasingly connected. FATF’s new report on scam compounds, published on 5 November 2026, illustrates this development.
The report describes large-scale criminal networks operating across jurisdictions and relying on a combination of payment services, virtual assets, technology infrastructure and telecommunications to collect, move and launder criminal proceeds.
FATF describes scam compounds as one of the fastest-growing forms of transnational organised crime and estimates that they generate losses measured in tens of billions of dollars annually. For crypto businesses, this means fraud risk and AML risk increasingly need to be considered together.
DeFi is also moving onto the compliance agenda
The regulatory perimeter is becoming equally important for decentralised finance.
In July 2026, FATF warned that almost 93% of reporting jurisdictions had not yet implemented FATF standards in relation to qualifying DeFi arrangements, while only two jurisdictions surveyed had actually licensed or registered such arrangements.
FATF emphasised that labels such as “decentralised” do not automatically remove an arrangement from the scope of AML obligations where identifiable persons exercise sufficient control or influence over the activity.
For founders, investors and protocol developers, this creates an important planning issue. A business model designed today on the assumption that decentralisation automatically avoids regulated VASP status may face materially different regulatory treatment as implementation develops.
Grey lists and counterparty risk
FATF’s October Plenary also updated its lists of monitored jurisdictions. Bulgaria, Côte d’Ivoire, the Democratic Republic of the Congo and Monaco were removed from increased monitoring after completing their action plans.
At the same time, FATF expressed significant concern regarding the pace of reforms in Vietnam. Iran, Myanmar and North Korea remain subject to FATF’s high-risk jurisdiction framework.
A FATF listing does not automatically prohibit business with a jurisdiction. But it can substantially affect risk assessments, enhanced due-diligence requirements, banking relationships, correspondent services and the willingness of counterparties to process transactions.
For crypto businesses, these consequences can be particularly significant because relationships with banks and payment providers remain essential to converting between fiat currency and digital assets.
What should crypto businesses review?
The new FATF initiative should prompt international crypto businesses to reassess whether their compliance architecture adequately reflects jurisdiction and counterparty risk.
This includes understanding where counterparties are licensed, whether Travel Rule requirements are implemented effectively, how information is exchanged between VASPs, and what procedures apply when a counterparty cannot provide adequate originator or beneficiary information. Sanctions screening should also be integrated into the same framework.
Businesses should consider whether their systems can identify exposure not only to sanctioned individuals but also to high-risk exchanges, wallet infrastructure and jurisdictions presenting elevated AML or proliferation-financing concerns.
Contracts with custodians, liquidity providers, exchanges and payment processors should allocate responsibility clearly for KYC, AML information exchange, sanctions compliance and regulatory cooperation.
AryaTech perspective
The direction of FATF policy is increasingly clear. The international crypto AML framework is moving from rule adoption toward demonstrable implementation and enforcement.
For businesses operating across borders, that makes jurisdiction selection, counterparty due diligence and contractual compliance increasingly important.
AryaTech’s Cross-Border Crypto AML & Jurisdiction Risk Review can assist exchanges, custodians, token businesses and Web3 companies in assessing regulatory exposure across jurisdictions, reviewing VASP counterparties, evaluating Travel Rule and sanctions processes and strengthening contractual protections with service providers.
The objective is not simply to determine whether a crypto business has an AML policy. It is to determine whether its international network of customers, counterparties, jurisdictions and infrastructure can withstand increasingly coordinated regulatory scrutiny.
Selected References
Financial Action Task Force, Outcomes of the FATF Plenary, 28–30 October 2026
FATF announced the targeted review and accelerated follow-up process concerning virtual assets and VASPs.
https://www.fatf-gafi.org/en/publications/Fatfgeneral/outcomes-fatf-plenary-october-2026.html
FATF, Launch of Targeted Review Process to Accelerate Global Implementation of FATF Standards Relating to Virtual Assets, 30 October 2026
https://www.fatf-gafi.org/en/publications/Fatfrecommendations/launch-targeted-review-strengthen-standards-virtual-assets.html
FATF, Seventh Targeted Update on Implementation of the FATF Standards on Virtual Assets/VASPs, 16 July 2026
https://www.fatf-gafi.org/en/publications/Fatfrecommendations/targeted-updated-virtualassets-vasps-2026.html
FATF, Combating End-to-End Illicit Financial Flows Linked to Scam Compounds, 5 November 2026
https://www.fatf-gafi.org/en/publications/Methodsandtrends/combating-illicit-financial-flows-linked-to-scam-compounds.html
FATF, Targeted Report on Regulatory Challenges from DeFi, 21 July 2026
https://www.fatf-gafi.org/en/news/targeted-report-decentralised-finance-2026.html
Reuters, “FATF removes Bulgaria, Congo, Ivory Coast and Monaco from ‘grey list’ but leaves Vietnam on”, 30 October 2026.
Provides independent reporting on the October FATF Plenary and the commercial effects of FATF monitoring.
This article is intended for general information and does not constitute legal advice.